
Special Economic Zones (SEZs) have become a tool for industrial development amongst many countries across the world. In simple words, SEZ is an area within a country where the state systematically promotes economic activity through various incentives like tax and duty exemptions. The aim is to encourage businesses and entrepreneurs to step forward and invest. This not only helps businesses thrive but also helps countries attain economic development.
The first modern SEZ was established in 1959 at Shannon in Ireland. Since then, many other countries have followed the precedent set by Ireland. Today, the majority of the countries across the globe have SEZs. As per World Investment Report 2019, currently, there are almost 5,400 SEZs in the world out of which more than 1,000 SEZs were developed in the last five years. The reports suggest that number of SEZs is expected to rise, keeping in view its successful contribution to economic growth.
A lot of countries have experimented with SEZs for economic growth, but so far it’s China that has the most successful experience with SEZs. China has attained phenomenal economic growth via its SEZs. Especially, China’s successful experiment with Shenzen SEZ has become worth following for Countries from Asia to Latin America. Shenzen used to be a small village in China in the 1980s; however, once China declared it as SEZ, it turned out to be a great contributor to China’s economic development. One other testimony to China’s successful record with SEZs is that, as per some estimates, SEZs all over the world have created 66 million jobs of which 30 million jobs were located in China alone.
How Canadian Casino Payment Methods Evolved: A Look at https://casizoid.org/
The Canadian online gambling market has undergone a remarkable transformation over the past two decades, and nowhere is that change more visible than in the payment infrastructure supporting it. What began as a fragmented, legally ambiguous system relying heavily on credit cards and wire transfers has evolved into a sophisticated ecosystem of digital wallets, prepaid cards, cryptocurrency options, and real-time banking integrations. Understanding how this evolution unfolded requires looking at the regulatory shifts, banking industry responses, and consumer demand patterns that collectively reshaped how Canadians fund their online casino accounts.
The Early Years: Credit Cards and the Legal Grey Zone
In the late 1990s and early 2000s, when online casinos first became accessible to Canadian players, credit cards were the dominant payment method by a wide margin. Visa and Mastercard transactions processed seamlessly, and players faced little friction depositing funds at offshore-licensed operators. Canada’s legal framework at the time was rooted in the Criminal Code of 1985, which prohibited operating a gambling house but contained no specific provisions addressing internet-based wagering hosted outside the country. This ambiguity meant players could participate without clear legal consequence, and banks had no explicit mandate to block gambling-related transactions.
That relative openness began to close around 2002 and 2003, when major Canadian financial institutions — responding to pressure from U.S. regulators following the passage of early American anti-gambling legislation — started voluntarily declining credit card transactions coded under Merchant Category Code 7995, the standard identifier for gambling merchants. This wasn’t a Canadian law but a risk management decision by the banks themselves. The practical effect was significant: players who had previously deposited with a Visa card suddenly found their transactions declined, pushing demand toward alternative channels.
The immediate response from the market was a surge in the use of third-party payment processors, most notably Neteller and Moneybookers (later rebranded as Skrill). Both companies established Canadian operations and allowed players to load funds via bank transfers or credit cards at the processor level, then transfer those pooled funds to casino accounts without triggering the gambling merchant code. By 2005, Neteller alone reportedly processed over 80 percent of online gambling transactions in North America, a statistic that illustrated both the demand for alternatives and the fragility of a system built around a single intermediary.
The Neteller Shock and the Rise of Prepaid Solutions
In January 2007, U.S. federal authorities arrested Neteller’s co-founders and the company immediately suspended services to American and Canadian customers. The move sent shockwaves through the Canadian online gambling community. Overnight, the most widely used payment channel disappeared, and players with balances held in their Neteller accounts faced weeks of uncertainty about whether they could recover their funds. Most eventually did, but the episode exposed a critical vulnerability: dependence on a single dominant processor operating in a regulatory grey zone.
The aftermath accelerated two parallel trends. First, Skrill stepped into the vacuum and expanded its Canadian user base rapidly, though it too faced periodic restrictions on gambling-related transactions depending on the province. Second, prepaid solutions — particularly Paysafecard, which had been operating in Europe since 2000 and entered the Canadian market around 2009 — gained significant traction. Paysafecard’s model was appealing precisely because it required no bank account linkage and no personal financial data transmitted to the casino. A player purchased a voucher at a convenience store or gas station, entered a 16-digit PIN at the casino cashier, and the transaction was complete. For privacy-conscious players or those whose banks were blocking gambling deposits, this was a practical and immediate solution.
Around this same period, platforms aggregating casino reviews and payment method comparisons began emerging to help Canadian players navigate the fragmented landscape. Resources like https://casizoid.org/ reflect how the industry responded to consumer confusion by building structured informational hubs that explain which payment methods are accepted at which operators, how withdrawal timelines differ, and what verification requirements apply — practical guidance that became increasingly necessary as the payment ecosystem grew more complex.
Provincial Regulation and the Interac Turning Point
The most significant structural shift in Canadian casino payment methods came not from a single event but from a gradual regulatory evolution at the provincial level. Beginning with the British Columbia Lottery Corporation’s launch of PlayNow.com in 2004 and accelerating through Ontario’s expansion of its iGaming framework in 2022, provincial governments began licensing and operating their own online gambling platforms. This created a bifurcated market: provincially regulated sites with direct banking integrations, and offshore-licensed operators serving the same Canadian players under different technical arrangements.
For provincially regulated platforms, the payment story changed dramatically. Interac — Canada’s domestic debit network, operational since 1984 and deeply embedded in Canadian retail banking — became the preferred deposit and withdrawal method. Interac Online and later Interac e-Transfer allowed players to move funds directly from their bank accounts without credit card involvement and without third-party processors. The appeal was straightforward: transactions settled quickly, fees were minimal, and the familiar Interac brand carried trust built over decades of everyday retail use. By 2019, Interac e-Transfer had become the most widely used online payment method in Canada across all categories, processing over 486 million transactions annually according to Payments Canada data.
Offshore operators serving Canadian players adapted by integrating Interac e-Transfer through payment aggregators, though the technical implementation was more complex than on regulated platforms. Processing times and success rates varied, and players sometimes encountered declined transfers when their bank’s fraud detection systems flagged gambling-related recipients. This inconsistency kept demand alive for alternative methods even as Interac grew dominant.
Cryptocurrency, Instant Banking, and the Current Landscape
The period from 2017 onward introduced cryptocurrency as a meaningful payment option in the Canadian online casino market, though its adoption curve has been more gradual than early advocates predicted. Bitcoin was the initial entry point, with a small number of operators accepting it by 2014, but the volatility of cryptocurrency values created practical problems for both players and operators trying to manage bankroll stability. Ethereum and stablecoins like USDT addressed some of these concerns, and by 2022 a noticeable segment of Canadian players — particularly younger demographics comfortable with digital assets — were actively seeking crypto-accepting casinos specifically for the combination of transaction speed and reduced identity verification requirements.
Simultaneously, a new category of payment technology emerged under various names — instant banking, open banking payments, or bank-to-bank transfers facilitated by regulated fintech intermediaries. Services like iDebit and InstaDebit in Canada, and later MuchBetter, allowed players to authenticate directly with their bank and authorize transfers without sharing account credentials with the casino. These methods combined the trust of bank-level security with the speed of digital wallets, typically settling deposits in seconds and withdrawals within one to three business days.
The Ontario iGaming market, which opened to private operators in April 2022 under the Alcohol and Gaming Commission of Ontario (AGCO), formalized many of these payment dynamics. Licensed operators in Ontario are required to meet specific responsible gambling standards, including deposit limit functionality, and payment processors serving those operators must comply with anti-money laundering regulations under FINTRAC oversight. This regulatory structure has pushed payment providers to build more sophisticated compliance infrastructure, which in turn has raised the baseline quality and reliability of payment processing across the licensed market.
Casizoid.org and similar information platforms have tracked these regulatory developments closely, reflecting how the informational needs of Canadian players have shifted from basic questions about which sites accept Canadian dollars to more nuanced concerns about withdrawal speeds, fee structures, identity verification requirements, and which payment methods remain available in specific provinces.
The evolution of Canadian casino payment methods is ultimately a story about the interaction between consumer demand, regulatory pressure, and financial technology innovation. Players consistently sought convenience, privacy, and reliability; banks and regulators imposed constraints that shaped which solutions were viable at any given moment; and the payment industry responded with new products filling each successive gap. The current landscape — where a Canadian player might choose between Interac e-Transfer, Paysafecard, a digital wallet, or cryptocurrency depending on their priorities — represents the accumulated outcome of two decades of adaptation. As provincial regulation continues to mature and open banking frameworks develop further under federal fintech policy, the payment options available to Canadian casino players will almost certainly continue to evolve, adding new layers of complexity and choice to an already sophisticated market.
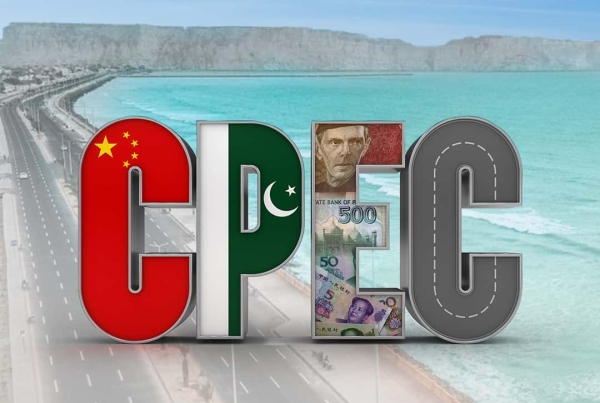
Thanks to CPEC, Pakistan is currently at the doorstep of attaining economic development via SEZs. As CPEC is about to step into the Second Phase, China is more focused on industrial development in Pakistan. In this regard, 9 SEZs have been planned in which one SEZ will be established in Punjab, Khyber Pakhtunkhwa, Baluchistan, and Islamabad respectively. Two SEZs will be established in Sindh and one SEZ will be established in erstwhile Federally Administered Tribal Areas (FATA), Azad Kashmir and Gilgit Baltistan respectively.
Below is the list of 9 SEZs that will be established in Pakistan in the wake of CPEC.
- Rashakai Economic Zone, M-1,
- NowsheraDhabeji Special Economic Zone
- Bostan Industrial Zone
- Allama Iqbal Industrial City, Faisalabad
- ICT Model Industrial Zone, Islamabad
- Industrial Park Pakistan Steel Mills Port Qasim
- Mirpur Industrial Zone, AJK
- Mohmand Marble City
- Moqpondass SEZ Gilgit-Baltistan
The launch of SEZs under CPEC is nothing less than a godsend for Pakistan. This will not only prove to be fruitful in paving the way for economic and industrial development in Pakistan but will also improve foreign direct investments in Pakistan. As per Adviser to PM on Commerce and Investment Abdul Razak Dawood. SEZs launched under CPEC will play a huge role in the socio-economic development of Pakistan. They will attract more investments; they will accelerate industrialization; they will create job opportunities and, more importantly, they will result in export-led economic growth in Pakistan.
In addition to that, SEZs will turn out to be a boon for local industries and entrepreneurs in Pakistan. Not only will they have a chance to expand their scope globally in a business-friendly conducive environment, but will also have a chance to interact with international firms including business firms from China.
More importantly, SEZs will prove to be a means of knowledge and skills exchange between Pakistan and China. It’s a fact that Pakistan currently does not have the required workforce to deal successfully with the operation of SEZs. In this regard, China will certainly provide training to people in Pakistan for the development of a capable workforce. This will create a lot of employment opportunities in Pakistan.
While commenting upon the SEZs’ potential to create employment opportunities in Pakistan, a Senior Official from Board of Investment (BOI) recently said in an interview, “The four SEZs including Rashakai M-1 Nowshera; Dhabeji Thatta; Allama Iqbal Industrial City Faisalabad and Bostan Balochistan would create around 475,000 direct and 1,000,000 indirect jobs all across the country.”
Apart from creating employment opportunities, the development of SEZs carries lucrative prospects for the growth of the real estate sector in Pakistan. Majority of the land developers are showing keen interest to invest in the development of infrastructure at SEZs. As a pioneer land developer, Rafi Group believes that SEZs will boost the confidence of investors in the property sector across Pakistan.
For readers’ convenience, Rafi Group is the most trusted land development company in the construction sector across Pakistan with a rich legacy of 43 years. Headquartered in Lahore, it has amazing real estate projects to its name. Currently, it has been developing Green Palms Housing Project in Gwadar on a principle of lean construction and holds the distinction of being a pioneer land developer in Gwadar’s real estate. Envisioned to meet the housing needs in Gwadar, Green Palms Housing Project is presently the largest private housing project in Chinese-backed Gwadar Smart Port City with an approved area of over 1065 acres of land. It is developing on a fast-track basis and has an approved NOC from Gwadar Development Authority (GDA). The housing project offers residential and commercial plots at affordable rates and is located adjacent to Makran Coastal Highway.
In short, the establishment of SEZs is one of the major developments during the Second Phase of CPEC. That gives Pakistan a golden chance to learn from China’s rich experience about how to attain economic development via SEZs. Currently, the Government has been seriously working on four SEZs that comprise of Rashakai M-1 Nowshera, Dhabeji Thatta, Allama Iqbal Industrial City Faisalabad, and Bostan Balochistan. To capitalize on the potential of SEZs, it’s important that Government not only provides all kinds of incentives to businesses but also ensures the provision of all basic amenities like gas, water, and electricity in these SEZs. More importantly, the Government should provide a secure environment for the operation of businesses in SEZs. Also, for the success of SEZs, socio-economic conditions of adjacent areas to SEZs must be improved. For this, local capacity building should be the top priority. In this regard, Pakistan can collaborate with China and make sure that locals are skilled enough for the employment opportunities coming in the wake of SEZs.